

This article provides general educational information about inherited IRA rules and is not personalized tax, legal, or financial advice. Consult with qualified professionals for guidance specific to your situation.
When you inherit an IRA, you’re receiving more than just money. You’re stepping into a complex web of tax rules, distribution requirements, and strategic decisions that can dramatically impact how much you actually keep. The difference between making the right moves and the wrong ones? That could easily mean $100,000 or more over the next decade.
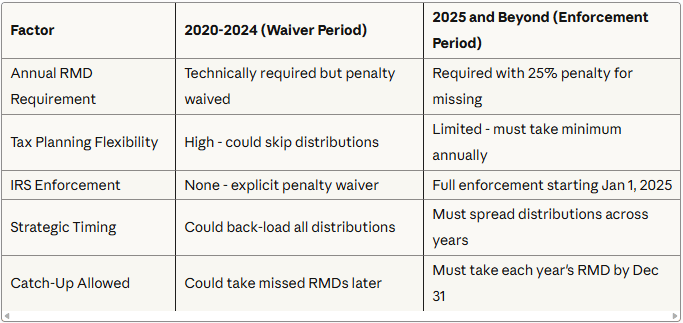
The 2025 enforcement change in one paragraph: The IRS finalized regulations in 2024 that fundamentally changed inherited IRA distributions starting January 1, 2025 — now in its second full year as of 2026. If you inherited an IRA after 2019 from someone who had already started taking Required Minimum Distributions (RMDs), you must take annual RMDs during the 10-year period — not just empty the account by year 10. The penalty waiver that protected beneficiaries from 2020 through 2024 has expired. Missing an annual RMD triggers a 25% penalty on the amount you should have withdrawn.
The 2025 Rule Change That Affects Inherited IRA Distributions
Starting January 1, 2025, the IRS began enforcing annual RMD requirements for inherited IRAs that were previously waived from 2020 through 2024. This is not a minor technical update.
What changed:
The IRS final regulations issued in July 2024 confirmed that if the original IRA owner had already started taking RMDs before death (had reached their Required Beginning Date), beneficiaries must:
- Take annual RMDs during years 1 through 9 of the 10-year period, AND
- Empty the account by December 31 of year 10
From 2020 through 2024, many beneficiaries and tax professionals interpreted the waiver guidance as meaning annual RMDs weren’t actually required. That interpretation is now definitively wrong.
The penalty for missing an annual RMD:
- 25% excise tax on the amount you should have withdrawn
- Reduced to 10% if you take the missed amount and report the tax within the IRS correction window (generally by the end of the second year after the miss), and it can be waived for reasonable cause on Form 5329
- On a $50,000 required distribution: a $12,500 penalty ($5,000 if corrected in time)
- You still owe income tax on the distribution when you eventually take it
- The IRS is not sending reminder notices
| Original owner at death | Annual RMDs during the 10-year period? | Final distribution deadline |
|---|---|---|
| Died before their required beginning date (for example, age 68 with an RMD age of 73) | No — full flexibility on timing | December 31 of year 10 |
| Died on or after their required beginning date (for example, age 78) | Yes — annual RMDs in years 1 through 9 | December 31 of year 10 |
RBD = Required Beginning Date for RMDs, which is April 1 following the year the owner turns 73 — or 75 for those born in 1960 or later. An owner who dies at their RMD age (or the following year) may or may not have reached it, depending on whether that April 1 had passed.
Real-World Impact: What This Means If You Inherited in 2020 Through 2024
Scenario: You inherited a $400,000 IRA in 2022 from your mother who was 78 when she passed (she had been taking RMDs). Under the waiver, you didn’t take RMDs in 2023 or 2024. You might have thought you could wait until 2032 (year 10) to take everything.
What you actually owe:
You must take your RMD each year by December 31 — or face a 25% penalty for that year. Your RMD is calculated by dividing the prior year-end account balance by your life expectancy factor from the IRS Single Life Expectancy Table.
- If you’re 50 years old, your life expectancy factor is approximately 36.2 years
- RMD: $400,000 / 36.2 = $11,050
- Miss the deadline: $2,763 penalty (25% of $11,050) plus income taxes when you eventually take it
For 2023 and 2024, the IRS waived penalties — you don’t owe back penalties for those years. But you must take RMDs for 2025, 2026, 2027, 2028, 2029, 2030, and 2031, then empty the account completely by December 31, 2032.
Understanding Who You Are in the Eyes of the IRS
The IRS categorizes beneficiaries into 3 distinct groups. Your group membership dictates your options, timelines, and tax consequences.
Spousal Beneficiaries: Maximum Flexibility
Spousal beneficiaries have options that no one else gets.
Option 1: Roll over into your own IRA
This is the most powerful option. The IRA becomes yours, you’re not subject to any immediate distribution requirements, and you won’t face RMDs until you reach age 73 (or age 75 if you were born in 1960 or later). The clock resets entirely.
Option 2: Remain as a beneficiary
This matters if you’re under age 59½ and might need access to money before traditional retirement age. When you remain as a beneficiary of an inherited spousal IRA, the 10% early withdrawal penalty is waived entirely. If you rolled the IRA into your own account, a $50,000 withdrawal would cost an extra $5,000 in penalties.
The tradeoff depends on whether your spouse had reached their required beginning date. If they had, remaining as a beneficiary means annual RMDs based on your life expectancy starting the year after their death. If they died before it, you can wait until the year your spouse would have reached RMD age (73, or 75 if born 1960 or later) before RMDs begin. Rolling over instead lets you wait until your own RMD age.
Option 3: Keep in the deceased spouse’s name temporarily, then convert to your own IRA later when it’s more advantageous. This flexibility is exclusively available to spouses.
Real-world scenario: Maria, age 62
Maria inherits her husband’s $650,000 traditional IRA. Her husband was 67 when he passed. Maria has her own IRA worth $280,000 and is still working, earning $110,000 annually.
| Strategy | Details |
|---|---|
| Spousal rollover | Combined IRA of $930,000. Born after 1960, Maria has no RMDs until age 75 (13 more years of growth). At 6% annually, the IRA could reach ~$1,984,000 by age 75. First RMD at 75 (Uniform Lifetime Table factor 24.6): ~$80,600 |
| Remain as beneficiary | Her husband died at 67, before his required beginning date, so no RMDs are due until the year he would have turned 73. After that, annual RMDs based on her own life expectancy from the IRS Single Life Table. Penalty-free access before 59½ doesn’t matter here, since she’s already 62 |
The spousal rollover gives Maria control over timing — potentially letting her delay distributions until after retirement when her tax rate may be lower.
Non-Spouse Designated Beneficiaries: The 10-Year Rule
Named individual beneficiaries (children, siblings, friends, parents) face the 10-year distribution rule.
The core requirement: Empty the entire inherited IRA by December 31 of the 10th year following the year of the original owner’s death.
Annual RMD requirement (the 2025 change):
- If the original owner died before their Required Beginning Date: No annual RMDs required during the 10-year period. You can let the account grow and take everything in year 10.
- If the original owner died after their Required Beginning Date: Annual RMDs required during years 1 through 9, AND the account must be emptied by year 10.
Understanding the Annual RMD Requirement
Your Annual RMD Calculation Formula:
Account balance on December 31 of prior year / Your life expectancy factor (IRS Single Life Table)
Example: You’re 45 years old, inherited a $500,000 IRA from a parent who was taking RMDs.
- Year 1 RMD: $500,000 / 41.0 (IRS Single Life Table factor at age 45) = $12,195
- Each subsequent year, you divide the prior year-end balance by your remaining life expectancy (which decreases by 1 each year)
This requirement fundamentally changes your tax planning flexibility. Without it, you could strategically time all distributions to occur in low-income years. With it, you face a floor on distributions each year regardless of your tax situation. You gain flexibility only in choosing to take more than the minimum in any given year.
3 Distribution Approaches: A Case Study
Scenario for all 3 approaches:
- You inherit a $500,000 traditional IRA from a parent who was 76 and had already started RMDs
- You are 45 years old at the time of inheritance
- You earn $85,000 per year from your job (stays consistent except where noted)
- You are a single filer
- The inherited IRA grows at 6% annually
- Annual RMDs are required, AND the account must be empty by year 10
- The life expectancy factor starts at 41.0 (IRS Single Life Table, age 45) and drops by 1 each year
- Taxes use the 2026 single brackets and $16,100 standard deduction, held constant; “federal tax on distribution” is the extra federal income tax each distribution adds to your salary
Approach 1: Take Only Required RMDs, Then Empty in Year 10
Takes the minimum required each year, lets the balance grow, then takes everything remaining in year 10.
| Year | Beginning balance | Factor | RMD | Distribution | Total income | Top bracket | Federal tax on distribution |
|---|---|---|---|---|---|---|---|
| 1 | $500,000 | 41.0 | $12,195 | $12,195 | $97,195 | 22% | $2,683 |
| 2 | $517,073 | 40.0 | $12,927 | $12,927 | $97,927 | 22% | $2,844 |
| 3 | $534,395 | 39.0 | $13,702 | $13,702 | $98,702 | 22% | $3,015 |
| 4 | $551,934 | 38.0 | $14,525 | $14,525 | $99,525 | 22% | $3,195 |
| 5 | $569,654 | 37.0 | $15,396 | $15,396 | $100,396 | 22% | $3,387 |
| 6 | $587,514 | 36.0 | $16,320 | $16,320 | $101,320 | 22% | $3,590 |
| 7 | $605,465 | 35.0 | $17,299 | $17,299 | $102,299 | 22% | $3,806 |
| 8 | $623,456 | 34.0 | $18,337 | $18,337 | $103,337 | 22% | $4,034 |
| 9 | $641,427 | 33.0 | $19,437 | $19,437 | $104,437 | 22% | $4,276 |
| 10 | $659,309 | — | — | $659,309 | $744,309 | 37% | $215,525 |
Results:
| Metric | Amount |
|---|---|
| Total distributions | $799,447 |
| Federal taxes (years 1 through 9) | $30,830 |
| Federal taxes (year 10) | $215,525 |
| Total federal taxes | $246,355 |
| Effective tax rate on distributions | 30.8% |
| After-tax amount | $553,092 |
The counterintuitive result: Despite paying the most in taxes of all 3 approaches, Approach 1 puts the most money in your pocket. The extra $122,590 in distributions (generated by letting the account grow longer) more than compensates for the extra $90,300 in taxes. You end up with $32,290 more than Approach 2 and $11,189 more than Approach 3.
Key principle: Minimizing your tax rate and maximizing your after-tax wealth are not the same goal. Approach 1 is the least tax-efficient strategy but the most wealth-maximizing strategy in this comparison. One caveat: these totals add up after-tax distributions and don’t count what you could earn by investing money withdrawn in earlier years, which narrows Approach 1’s lead.
Best fit: You don’t need distributions during years 1 through 9, can handle a large year 10 tax bill, and your primary goal is maximizing total after-tax wealth.
Approach 2: Strategic Annual Distributions Above the Minimum
Takes larger distributions each year ($80,000 annually starting in year 3) while still meeting RMD requirements.
| Year | Beginning balance | Factor | RMD | Distribution | Total income | Top bracket | Federal tax on distribution |
|---|---|---|---|---|---|---|---|
| 1 | $500,000 | 41.0 | $12,195 | $12,195 | $97,195 | 22% | $2,683 |
| 2 | $517,073 | 40.0 | $12,927 | $12,927 | $97,927 | 22% | $2,844 |
| 3 | $534,395 | 39.0 | $13,702 | $80,000 | $165,000 | 24% | $18,464 |
| 4 | $481,659 | 38.0 | $12,675 | $80,000 | $165,000 | 24% | $18,464 |
| 5 | $425,758 | 37.0 | $11,507 | $80,000 | $165,000 | 24% | $18,464 |
| 6 | $366,504 | 36.0 | $10,181 | $80,000 | $165,000 | 24% | $18,464 |
| 7 | $303,694 | 35.0 | $8,677 | $80,000 | $165,000 | 24% | $18,464 |
| 8 | $237,116 | 34.0 | $6,974 | $80,000 | $165,000 | 24% | $18,464 |
| 9 | $166,543 | 33.0 | $5,047 | $80,000 | $165,000 | 24% | $18,464 |
| 10 | $91,735 | — | — | $91,735 | $176,735 | 24% | $21,280 |
Results:
| Metric | Amount |
|---|---|
| Total distributions | $676,857 |
| Total federal taxes | $156,055 |
| Effective tax rate on distributions | 23.1% |
| After-tax amount | $520,802 |
The tradeoff: Approach 2 is the most tax-efficient strategy (lowest effective rate, $90,300 less in taxes than Approach 1) — but it puts the least money in your pocket. By removing money from the tax-deferred account earlier, you sacrifice investment growth. The $90,300 saved in taxes is less valuable than the additional $122,590 in distributions Approach 1 generated.
Best fit: You need consistent cash flow during the 10-year period, want to avoid a single year of very high income (IRMAA surcharges, Medicare impacts, etc.), or value tax smoothing and certainty over maximum wealth accumulation.
Approach 3: Time Distributions Around Income Changes
You plan a sabbatical in year 6 when your income drops to $20,000. You take $250,000 during that low-income year and minimum RMDs in all other years.
| Year | Beginning balance | Factor | RMD | Distribution | Salary | Total income | Top bracket | Federal tax on distribution |
|---|---|---|---|---|---|---|---|---|
| 1 | $500,000 | 41.0 | $12,195 | $12,195 | $85,000 | $97,195 | 22% | $2,683 |
| 2 | $517,073 | 40.0 | $12,927 | $12,927 | $85,000 | $97,927 | 22% | $2,844 |
| 3 | $534,395 | 39.0 | $13,702 | $13,702 | $85,000 | $98,702 | 22% | $3,015 |
| 4 | $551,934 | 38.0 | $14,525 | $14,525 | $85,000 | $99,525 | 22% | $3,195 |
| 5 | $569,654 | 37.0 | $15,396 | $15,396 | $85,000 | $100,396 | 22% | $3,387 |
| 6 | $587,514 | 36.0 | $16,320 | $250,000 | $20,000 | $270,000 | 32% | $57,314 |
| 7 | $357,764 | 35.0 | $10,222 | $10,222 | $85,000 | $95,222 | 22% | $2,249 |
| 8 | $368,395 | 34.0 | $10,835 | $10,835 | $85,000 | $95,835 | 22% | $2,384 |
| 9 | $379,014 | 33.0 | $11,485 | $11,485 | $85,000 | $96,485 | 22% | $2,527 |
| 10 | $389,580 | — | — | $389,580 | $85,000 | $474,580 | 35% | $119,367 |
Results:
| Metric | Amount |
|---|---|
| Total distributions | $740,867 |
| Total federal taxes | $198,964 |
| Effective tax rate on distributions | 26.9% |
| After-tax amount | $541,903 |
Where it lands: Middle ground. More wealth than Approach 2, less than Approach 1. The sabbatical year absorbs $250,000 at favorable rates (income of only $20,000), but a substantial year 10 balance still creates a tax spike.
Best fit: You have a predictable temporary income reduction window (sabbatical, career break, early retirement bridge, business startup, maternity/paternity leave) that you can plan around.
Comparison: All 3 Approaches
| Approach 1 | Approach 2 | Approach 3 | |
|---|---|---|---|
| Total distributions | $799,447 | $676,857 | $740,867 |
| Total federal taxes | $246,355 | $156,055 | $198,964 |
| Effective tax rate | 30.8% | 23.1% | 26.9% |
| After-tax wealth | $553,092 | $520,802 | $541,903 |
The surprising truth: The highest-tax approach delivers the most after-tax wealth. Tax efficiency and wealth maximization are not synonyms.
Eligible Designated Beneficiaries: The Exception to the 10-Year Rule
The SECURE Act created a special category that can still use a form of the old stretch IRA strategy — taking distributions over their life expectancy rather than facing the 10-year rule.
Who qualifies as an Eligible Designated Beneficiary:
- Surviving spouse
- Minor child of the deceased (until age 21 — then the 10-year rule kicks in)
- Disabled individuals (as defined by the IRS)
- Chronically ill individuals (as defined by the IRS)
- Any individual not more than 10 years younger than the deceased
That last category surprises people. If your 75-year-old brother names you as beneficiary and you’re 68, you qualify. But if you’re 66 when he dies at 80, you’re more than 10 years younger and face the 10-year rule.
Example: Thomas, age 71
Thomas inherits a $400,000 IRA from his 79-year-old sister. Because he’s within 10 years of her age, he qualifies as an Eligible Designated Beneficiary.
- Year 1 RMD: $400,000 / 18.0 (IRS Single Life Table factor at 71) = $22,222
- Year 2 RMD (after growth and first distribution): $392,000 / 17.0 = $23,059
This continues over Thomas’s life expectancy — potentially 18+ years — compared to the 10-year rule that would require full distribution by year 10. Over 17 years, Thomas might withdraw $600,000 or more from the original $400,000 IRA.
Non-Designated Beneficiaries: Estates, Charities, and Most Trusts
The least favorable category. Faces the most restrictive distribution rules.
The 5-year rule: If the original owner died before their Required Beginning Date, the entire IRA must be distributed by December 31 of the 5th year following the year of death — faster than the 10-year rule.
Why this matters for estate planning:
If your father’s $800,000 IRA names his estate as beneficiary (because he never updated the form after your mother passed) and he died before his required beginning date, the estate faces the 5-year rule. (If he had already reached it, payouts follow his remaining life expectancy instead.) Split equally among 3 siblings, each receives approximately $267,000 over 5 years.
If your father had named each of you individually as beneficiaries, you would each have had the 10-year rule — giving you far more flexibility to spread distributions across low-income years.
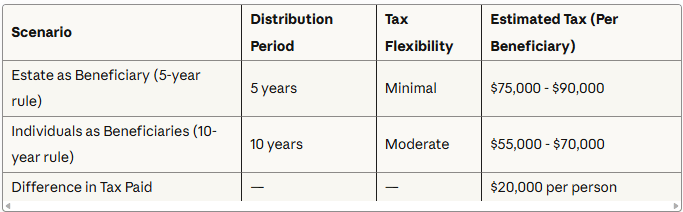
Multiply that across 3 beneficiaries, and the family pays $60,000 more in taxes simply because the beneficiary form wasn’t properly completed.
The Impact of the SECURE Acts: What Changed and Why It Matters
| Law | What it did |
|---|---|
| Pre-SECURE Act | “Stretch IRA” — distributions over your entire life expectancy. A 30-year-old could take tiny distributions for 50+ years |
| SECURE Act (2019) | Eliminated the stretch IRA for most beneficiaries. 10-year rule became the new standard for non-spouse beneficiaries |
| SECURE Act 2.0 (2022) | Increased RMD age from 72 to 73 (effective 2023) and eventually to 75 (effective 2033) |
| 2024 IRS Final Regulations | Confirmed annual RMD requirement during the 10-year period when original owner had started RMDs. Effective January 1, 2025 |
Why the Required Beginning Date matters — a side-by-side comparison:
Identical $600,000 inherited IRAs with one difference: the original owner’s age at death.
| Factor | Scenario A: death at age 70 (before RBD) | Scenario B: death at age 78 (after RBD) |
|---|---|---|
| Beneficiary | Age 45 at inheritance | Age 45 at inheritance |
| Starting IRA value | $600,000 | $600,000 |
| Annual RMDs required? | No annual RMDs during the 10-year period | Yes — annual RMDs based on life expectancy |
| Year 1 RMD | Not applicable | $600,000 / 41.0 = $14,634 |
| Distribution flexibility | Can take $0 in any year | Must take at least the RMD each year |
| Possible strategy | Take $0 in years 1-5 (high-earning years), then spread the balance over years 6-10 after an early retirement. At 6%, the account grows to about $803,000 by the end of year 5 | Take roughly $14,600-$23,300 a year in years 1-9 at 6% growth, then the remaining balance in year 10. Distributions can’t be pushed into low-income years |
| Year 10 distribution | Can be spread strategically before year 10 | Larger lump sum after 9 years of RMDs |
| Estimated additional tax cost | Baseline | Roughly $15,000-$30,000 more over 10 years for a beneficiary in the 24% bracket (estimate) |
| Key advantage | Maximum tax-planning flexibility | Simple to manage: take each year’s RMD |
The original owner’s age at death determines whether you get complete distribution flexibility (death before RBD) or must take annual RMDs (death after RBD). This single factor can cost beneficiaries $15,000 to $30,000 in additional taxes over the 10-year period for a $600,000 inheritance.
How the 2025 One Big Beautiful Bill Act (OBBBA) Affects Your Planning
OBBBA, signed into law on July 4, 2025, didn’t change inherited IRA distribution rules — but it changed the tax landscape in which those distributions occur.
Key OBBBA Changes for Inherited IRA Beneficiaries
Standard deduction increases (permanent):
- Single filers: $16,100 (2025: $15,750)
- Married filing jointly: $32,200 (2025: $31,500)
- Indexed for inflation going forward
More of your income is protected from taxation before IRA distributions begin pushing you into higher brackets.
SALT deduction cap temporary increase (2025 through 2029):
- Old cap: $10,000
- 2026 cap: $40,400 for taxpayers earning under $505,000 (2025: $40,000 under $500,000)
- Gradual 1% annual increase through 2029
- Taxpayers over the MAGI threshold: cap reduced by 30% of income over that threshold (but not below $10,000)
Estate and gift tax exemption increase (starting 2026):
- $15 million per person (from approximately $13.99 million in 2025)
- With portability for surviving spouses: $30 million per couple, indexed for inflation
Federal Income Tax Brackets, Now Permanent Under OBBBA:
| Rate | 2026 Income Range (Single) | 2025 Income Range (Single) |
|---|---|---|
| 10% | $0 — $12,400 | $0 — $11,925 |
| 12% | $12,400 — $50,400 | $11,925 — $48,475 |
| 22% | $50,400 — $105,700 | $48,475 — $103,350 |
| 24% | $105,700 — $201,775 | $103,350 — $197,300 |
| 32% | $201,775 — $256,225 | $197,300 — $250,525 |
| 35% | $256,225 — $640,600 | $250,525 — $626,350 |
| 37% | Over $640,600 | Over $626,350 |
Plan your inherited IRA distributions with confidence — these brackets won’t sunset, they’ll simply keep adjusting for inflation each year the way the 2025-to-2026 move above did.
OBBBA Planning Opportunity: High-SALT-State Beneficiaries
Scenario: David, California resident
David inherited a $600,000 IRA in 2024 from his father who had been taking RMDs. Annual RMDs apply.
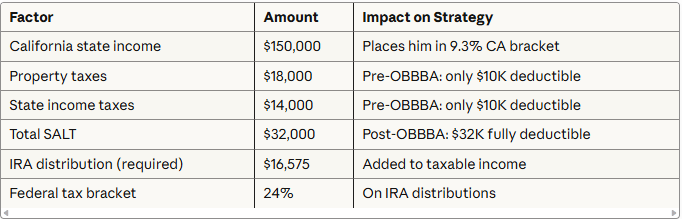
| Before OBBBA (2024) | After OBBBA (2025) | |
|---|---|---|
| State and local taxes paid | $32,000 | $32,000 |
| SALT cap | $10,000 | $40,000 |
| SALT deduction claimed | $10,000 | $32,000 |
| Other itemized deductions | $32,000 | $32,000 |
| Total itemized deductions | $42,000 | $64,000 |
The OBBBA benefit:
- Additional deduction: $22,000
- Tax savings at 24% federal rate: $5,280 per year
- Over the 2025 through 2029 window (5 years, before the cap reverts to $10,000): about $26,400 total savings
OBBBA Distribution Timing Strategy for High-SALT States
| Distribution strategy | Time period | SALT deduction available | Total federal tax (10 years) | After-tax inheritance |
|---|---|---|---|---|
| Even distribution (pre-OBBBA) | 2020-2029 | $10,000 cap | $152,000 | $448,000 |
| Even distribution (post-OBBBA) | 2025-2034 | Higher cap 2025-2029, $10,000 after | $128,000 | $472,000 |
| Front-load during the OBBBA window | 2025-2029 | Higher cap ($40,000 in 2025, $40,400 in 2026, rising 1% a year through 2029) | $118,000 | $482,000 |
Illustrative estimates for David’s profile; your figures depend on your income, state and itemized deductions.
David saves $34,000 by front-loading distributions during the 2025 through 2029 window when the higher SALT cap is available — even though his marginal tax rate is higher with larger distributions. The SALT deduction more than compensates for bracket creep. In 2026, that cap is $40,400 (up from $40,000 in 2025), with the MAGI phase-out threshold at $505,000 (up from $500,000). Both amounts are written into OBBBA, which raises them by 1% a year through 2029; they aren’t inflation adjustments.
The critical deadline: The SALT deduction enhancement expires after 2029, reverting to $10,000. If your 10-year distribution period extends beyond 2029, strongly consider taking larger distributions during 2025 through 2029.
Recommended distribution strategies by SALT deduction level:
| Your SALT situation | Recommended strategy | Tax benefit |
|---|---|---|
| SALT of $35,000-$40,400, MAGI under $505,000 (2026) | Accelerate distributions in 2025-2029 | About $6,000-$10,000 a year saved (estimate) |
| SALT of $20,000-$35,000, MAGI under $505,000 (2026) | Moderate front-loading in 2025-2029 | About $3,000-$6,000 a year saved (estimate) |
| SALT under $20,000 | No significant SALT benefit | Standard distribution timing |
| MAGI over $505,000 (2026) | The higher cap phases down (not below $10,000) | Consult a tax professional |
Senior Beneficiaries: Additional OBBBA Deduction (2025 Through 2028)
OBBBA added a temporary “bonus” deduction for taxpayers age 65 and older: $6,000 per person per year.
Phase-out thresholds:
| Filing Status | Phase-out begins | Phase-out rate |
|---|---|---|
| Single | $75,000 MAGI | Reduced by 6% of MAGI over the threshold |
| Married filing jointly | $150,000 MAGI | Reduced by 6% of MAGI over the threshold |
Example: Robert, age 67, inherited a $500,000 IRA. His income this year is $72,000. As a single filer age 65+, he qualifies for the full $6,000 deduction — saving approximately $1,065 in federal taxes for 2026, because after the $16,100 standard deduction and $2,050 additional deduction for age 65+, the $6,000 comes off income taxed at 22% and 12%. The $6,000 amount and $75,000 phase-out threshold are unchanged for 2026.
If Robert’s income was $85,000: $85,000 - $75,000 = $10,000 over threshold. Reduction: $10,000 x 6% = $600. His bonus deduction: $6,000 - $600 = $5,400.
The Tax Reality: What “Inheriting” an IRA Actually Means
When someone tells you they inherited a $1,000,000 IRA, they didn’t really inherit $1,000,000. They inherited a tax liability wrapped around an asset. The actual after-tax value could be $750,000, $650,000, or even less, depending on their tax situation and distribution strategy.
Traditional IRAs contain pre-tax dollars. Every dollar you withdraw gets added to your taxable income for that year.
Understanding Your Effective Tax Rate on Distributions
Jennifer, single, $95,000 salary, inherits a $400,000 IRA
She decides to take $40,000 per year over 10 years. Total income: $135,000.
2026 federal tax on $135,000 of income ($118,900 taxable after the $16,100 standard deduction):
| Bracket | Taxable income in bracket | Tax | Cumulative tax |
|---|---|---|---|
| 10% | $0-$12,400 | $1,240 | $1,240 |
| 12% | $12,400-$50,400 | $4,560 | $5,800 |
| 22% | $50,400-$105,700 | $12,166 | $17,966 |
| 24% | $105,700-$118,900 | $3,168 | $21,134 |
Without the distribution, her $95,000 salary ($78,900 taxable) would owe $12,070, so the $40,000 distribution adds $9,064.
- Federal tax on $40,000 distribution: ~$9,064 (2026 brackets and standard deduction)
- Effective rate on the distribution: ~22.7%
If Jennifer instead took $80,000 in one year (total income: $175,000), her effective rate on the distribution: ~23.3% — nearly identical, because both scenarios keep most of her income in the 24% bracket.
The real lesson: For someone at Jennifer’s income level, distribution size doesn’t dramatically change the tax rate as long as taxable income stays below $201,775 (the 2026 32% bracket threshold; $197,300 in 2025). The tax planning opportunity comes from timing distributions in years when her income temporarily drops — not from splitting large amounts into smaller ones while income stays constant.
Inherited Roth IRAs: A Completely Different Tax Story
Roth IRAs contain after-tax dollars — qualified distributions are completely tax-free. You’re still subject to the same 10-year distribution rules, but withdrawals are tax-free once the original owner’s Roth has met the 5-year holding period (contributions come out tax-free regardless).
Strategy difference: With a traditional inherited IRA, you carefully manage when you take distributions to avoid high-tax years. With an inherited Roth IRA, you can let the entire account grow for the full 10-year period, then withdraw everything by the end of year 10 — tax-free if the 5-year rule is met. (Because the original owner of a Roth IRA never has RMDs, inherited Roth IRAs don’t have annual RMDs during the 10-year period.)
Example: A $300,000 inherited Roth IRA growing at 6% annually for 10 years reaches approximately $537,000 — all withdrawn tax-free if the 5-year rule is met. You’ve received $237,000 in tax-free earnings over the period.
| Factor | Traditional IRA | Roth IRA |
|---|---|---|
| Initial inheritance | $300,000 | $300,000 |
| Tax on distributions | Ordinary income — often 24%-32% depending on timing | 0% once the 5-year rule is met |
| Strategic timing required | Yes, critical | Mainly whether to wait until year 10 |
| After-tax value (estimate) | $210,000-$240,000 | $300,000+ |
The Roth IRA inheritance is worth approximately $60,000 to $90,000 more after taxes — which is why estate planning often involves Roth conversions before death.
4 Common Mistakes That Cost Inherited IRA Beneficiaries
| Mistake | Penalty or extra tax | Your net loss | What you keep |
|---|---|---|---|
| Missing the year 10 deadline ($400,000 left) | $100,000 penalty (25%) + $96,000-$140,000 tax | $196,000-$240,000 | $160,000-$204,000 |
| Missing an annual RMD ($11,050) | $2,763 penalty (25%) | $2,763 | $397,237 |
| Lump sum in year 1 (vs. strategic) | About $65,000 excess tax | $65,000 | $335,000 |
| Back-loading everything to year 10 | About $45,000 excess tax | $45,000 | $355,000 |
| Never naming beneficiaries | Account passes to your estate | Varies widely | Unknown |
Estimates. The 25% penalty drops to 10% if you take the missed amount and report it within the IRS correction window, and it can be waived for reasonable cause.
Mistake 1: Missing the December 31 Deadline in Year 10
The IRS doesn’t send reminders. Miss it and you face a 25% penalty on the remaining balance (10% if you correct it within the correction window) plus income taxes on the entire amount. On a $400,000 remaining balance: $100,000 penalty plus approximately $96,000 to $140,000 in income taxes (depending on bracket) — reducing a $400,000 inheritance to $160,000 to $204,000.
Mistake 2: Missing Annual RMDs When Required
Many beneficiaries who inherited from 2020 through 2024 don’t realize they now have annual RMD requirements. Penalty: 25% of the amount you should have withdrawn.
Mistake 3: Taking Everything in Year 1
A $500,000 distribution on top of a $100,000 salary pushes you into the 35% bracket — roughly $160,000 in added federal income tax (2026 single brackets, standard deduction). Spreading it over 10 years at $50,000 annually might cost only $110,000 to $130,000 total.
Mistake 4: Failing to Update Your Own Beneficiary Designations
If you die during the 10-year period, the remaining inherited IRA balance passes according to your beneficiary designation. Your heirs must keep taking any required annual RMDs and still empty the account within the 10-year deadline (for most inherited IRAs, the one that already applies to you). No named beneficiary means it passes to your estate, adding probate delays and less control over who receives it.
Your Action Plan
Phase 1: Immediate Actions (First 30 Days)
Step 1: Confirm your beneficiary category and distribution requirements
Contact the financial institution and obtain:
- Official date of death and original owner’s date of birth
- Confirmation that the original owner had or had not started taking RMDs
- Your beneficiary designation status
- Current account value
Step 2: Determine if you have an RMD due this year
| Question | Answer | What it means |
|---|---|---|
| Did the original owner die before 2020? | Yes | Different (pre-SECURE Act) rules apply — consult a tax advisor |
| Are you the surviving spouse? | Yes | Special spousal options apply — see the spousal section above |
| Are you another eligible designated beneficiary? | Yes | The life expectancy method may apply |
| Had the original owner reached their required beginning date? | Yes | Annual RMDs required: take this year’s RMD by December 31 |
| Had the original owner reached their required beginning date? | No | No annual RMDs, but the account must be empty by December 31 of year 10 |
| Is it an inherited Roth IRA? | Yes | No annual RMDs; empty it by the end of year 10 |
Step 3: Calculate your RMD if required — our RMD calculator can run this for you
RMD = Account balance on December 31 of last year / Your life expectancy factor (IRS Single Life Table)
Example: You’re age 53, inherited $600,000 in 2022, account value was $650,000 on December 31, 2025.
- 2026 RMD = $650,000 / 33.4 (life expectancy for age 53) = $19,461
- Deadline: December 31, 2026
- Penalty for missing: $4,865 (25% of $19,461)
Phase 2: Strategic Planning (Days 30 Through 90)
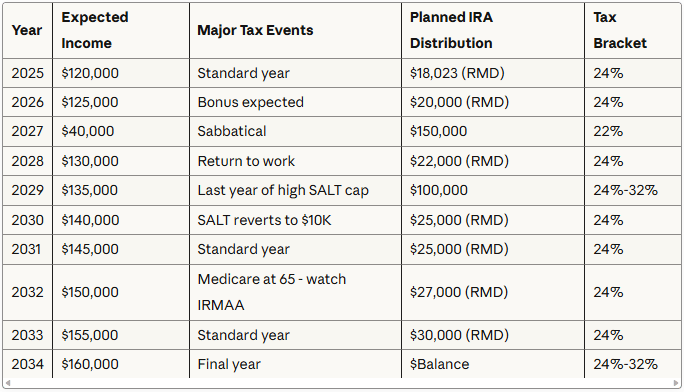
Step 4: Create your 10-year tax distribution strategy
Map out your income projection for the next 10 years. Look for planned career changes, retirement timing, sabbaticals, or other income shifts.
Step 5: Consider OBBBA opportunities (2025 through 2029)
If you’re in a high-SALT state, consider front-loading distributions while the $40,400 SALT cap (2026) is available. See the strategies by SALT level above.
Step 6: Set up automated tracking and reminders
Critical dates to calendar:
| Date | What’s due |
|---|---|
| December 31 (each year) | Annual RMD deadline |
| December 31 of year 10 | Final distribution deadline (2030 for 2020 inheritances, 2031 for 2021, 2032 for 2022, 2033 for 2023, 2034 for 2024) |
| April 1 following the year you turn 73 (75 if born 1960 or later) | Your own RMDs begin (if applicable) |
| October 15 (each year) | Review and adjust strategy based on year-to-date income |
Phase 3: Annual Maintenance
Annual review checklist (complete by November 30 each year):
| Task | Notes |
|---|---|
| Verify current account balance | Needed for next year’s RMD calculation |
| Calculate next year’s RMD | December 31 balance / life expectancy factor |
| Review current-year income | Actual vs. projected — adjust if needed |
| Check tax law changes | The higher SALT cap ends after 2029 and the senior deduction after 2028; OBBBA’s brackets and standard deduction are permanent |
| Update beneficiary designations | Your own beneficiaries for the inherited IRA |
| Confirm the distribution was taken | Get confirmation from the financial institution |
| Document for tax filing | Save all Forms 1099-R |
| Meet with your tax advisor | Review strategy and make adjustments |
Compliance Checklist (If You Inherited in 2020 Through 2024)
For inherited IRAs where the original owner HAD started RMDs:
| Inheritance year | RMD years waived | First RMD year required | Final distribution year | What to do now |
|---|---|---|---|---|
| 2020 | 2021-2024 | 2025 | 2030 | Take each year’s RMD by December 31 (the 2026 RMD is due December 31, 2026) |
| 2021 | 2022-2024 | 2025 | 2031 | Same |
| 2022 | 2023-2024 | 2025 | 2032 | Same |
| 2023 | 2024 | 2025 | 2033 | Same |
| 2024 | None needed (first RMD year was 2025) | 2025 | 2034 | Same |
If you missed your 2025 RMD, take it as soon as possible and file Form 5329 — the penalty drops to 10% within the correction window, and you can request a waiver for reasonable cause.
For inherited IRAs where the original owner had NOT started RMDs:
You have maximum flexibility — no annual RMDs required during the 10-year period. But you must still empty the account by December 31 of the 10th year following death.
When Professional Help Is Worth the Cost
| Inherited IRA Value | Professional Fees | Potential Tax Savings | ROI |
|---|---|---|---|
| Over $250,000 | $500 to $2,000 (one-time consultation) | $15,000 to $75,000 over 10 years | 750% to 3,750% |
| Over $1,000,000 | $2,500 to $5,000 annually | $100,000 to $300,000 over 10 years | 400% to 1,200% |
Consider professional help immediately if:
- You’re in a high-SALT state with income near $500,000
- You’re approaching Medicare age and concerned about IRMAA surcharges
- You inherited multiple IRAs from different people
- You’re a trust beneficiary
- The original owner had both traditional and Roth IRAs
- You’re planning major life changes (retirement, business sale, etc.)
| Warning sign | Why it matters | Recommended action |
|---|---|---|
| You haven’t taken any distributions from a 2020-2024 inherited IRA | You may have a missed 2025 RMD to correct, and the 2026 RMD is due December 31 | Call a tax advisor this week |
| Your financial institution says you don’t need RMDs | They may have outdated information | Verify with a tax professional |
| Your income varies significantly year to year | Standard distribution timing is likely suboptimal | Create a custom multi-year strategy |
| You inherited $1M+ | Tax impact can exceed $300,000 — needs expert planning | Hire both a tax advisor and a financial advisor |
| The account is titled incorrectly | Could disqualify inherited IRA treatment | Fix immediately with the custodian |
| No beneficiaries named on the inherited IRA | Assets could go to your estate | Update beneficiary forms now |
| Approaching age 65 | IRMAA surcharges could cost $4,000+ a year | Model the Medicare impact |
Quick Reference: Your Inherited IRA at a Glance
| Your situation | Annual RMDs required? | Distribution deadline | Key planning opportunity | Biggest risk |
|---|---|---|---|---|
| Inherited 2025, owner had started RMDs | Yes — starting 2026 | December 31, 2035 | Higher SALT cap through 2029 | Missing this year’s RMD (25% penalty) |
| Inherited 2024, owner had started RMDs | Yes — starting 2025 | December 31, 2034 | Full OBBBA SALT window | Missing this year’s RMD (25% penalty) |
| Inherited 2020-2023, owner had started RMDs | Yes — starting 2025 | 2030-2033 | Higher SALT cap (partial years) | Missing this year’s RMD (25% penalty) |
| Inherited 2020 or later, owner had NOT started RMDs (or a Roth IRA) | No | December 31 of year 10 | Maximum tax flexibility | Missing the final-year deadline |
| Inherited as a spouse | Depends on your choice | Varies by strategy | Rollover to delay RMDs | Choosing the wrong strategy for your age |
| Inherited as another eligible designated beneficiary | Yes, annually over your life expectancy | Generally your lifetime | Longest deferral possible | Not qualifying properly |
The 3 Rules That Matter Most
Rule 1: Know your deadline
- Annual RMDs required: December 31 every year
- Final distribution: December 31 of year 10
- Penalty for missing: 25% of required amount
Rule 2: Plan for taxes
- Every dollar is taxable income (except Roth IRAs and any nondeductible basis the owner reported on Form 8606)
- State taxes can add 0% to 13.3% on top of federal
- Strategic timing can save $50,000 to $150,000 on a $500,000 inheritance
Rule 3: Use the 2025 through 2029 OBBBA window
- Higher SALT deduction ($40,400 in 2026, up from $10,000 pre-OBBBA) expires after 2029
- If you’re in a high-tax state, front-load distributions during this window
- Potential savings: $30,000 to $70,000 for high-SALT taxpayers
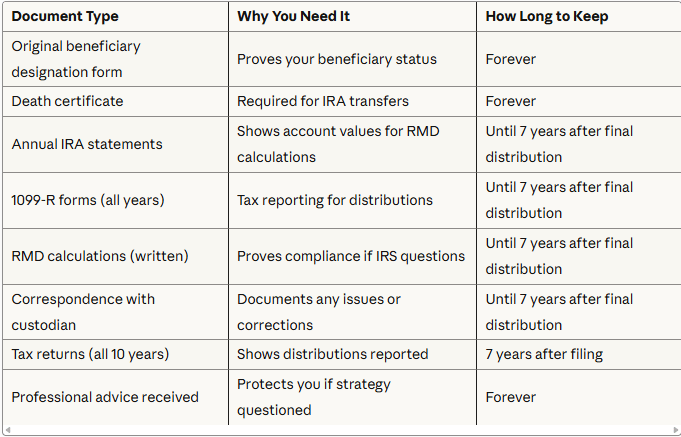
Document Retention Checklist
Keep these documents for the entire 10-year distribution period, plus 7 years after:
Frequently Asked Questions
I inherited the IRA in 2019, before the SECURE Act took effect. Do these rules apply to me?
No. IRAs inherited before January 1, 2020 are generally grandfathered under the old “stretch IRA” rules, letting you continue taking distributions over your own life expectancy rather than facing the 10-year rule. This is one of the few cases where the inheritance date fundamentally changes which rulebook applies.
What if I can’t determine whether the original owner had started RMDs?
Contact the financial institution that held the account — they’re required to have this on record and can confirm both the date of death and whether Required Minimum Distributions had begun. The legal test is the required beginning date: if the owner died on or after April 1 of the year after reaching RMD age (73, or 75 if born 1960 or later), annual RMDs apply to you — even if the owner hadn’t actually taken one yet.
Can I take my entire 10-year distribution in year 1 to simplify things?
Yes, nothing prevents front-loading, but as Mistake 3 above shows, dumping a large distribution into a single high-income year usually costs far more in taxes than spreading it out — even accounting for the account’s lost growth potential in some scenarios. Model the tax impact before choosing this route.
Do these rules apply to inherited Roth IRAs the same way?
The 10-year distribution timeline applies to both, but the tax consequences are completely different — inherited Roth IRA withdrawals are tax-free (assuming the original account met the 5-year rule), while inherited Traditional IRA withdrawals are fully taxable as ordinary income. See the “Inherited Roth IRAs” section above for the strategy difference.
What happens if the beneficiary is a minor child?
A minor child of the original owner qualifies as an Eligible Designated Beneficiary and can take distributions over their own life expectancy — but only until they turn 21, at which point the 10-year rule begins for whatever balance remains. This creates a two-phase distribution timeline that’s easy to miss if you’re not tracking the child’s age.
Further Reading
IRS resources:
- Publication 590-B: Distributions from Individual Retirement Arrangements
- IRS Retirement Plans: Beneficiary Rules and Life Expectancy Tables
Tax law changes:
- SECURE Act 2.0 provisions
- State tax impacts: Search “[Your state] department of revenue inherited IRA”
On this site:
- Year-end tax planning strategies for coordinating inherited IRA distributions with your broader tax picture
This article provides general educational information, not personalized tax, legal, or financial advice. Tax laws change frequently. Consult qualified professionals before making decisions about an inherited IRA. Individual circumstances vary, and strategies discussed may not be appropriate for your situation. The 2026 tax brackets and OBBBA provisions referenced reflect law as of this update.